What a Mortgage Survey Can Reveal
A house can look perfect from the sidewalk and still hide a problem that shows up right before closing. Maybe a fence sits on the wrong side of the property line. Maybe a garage was built too close to the neighbor’s lot.
A mortgage survey catches these issues early. It gives buyers, sellers and lenders a clear picture of what a property actually includes, not just what the listing says.
In Chicago, where lots are often narrow and older homes sit close together, this kind of survey plays a bigger role than many buyers expect.
Why Mortgage Surveys Matter During Property Transactions
A mortgage survey matters because it confirms the physical facts about a property before a loan closes. Lenders want to know exactly what they are financing. Buyers want to know exactly what they are paying for.
This type of survey shows property boundaries, structures and any visible features that could affect value or use. It gives everyone in the deal the same accurate information instead of relying on old records or assumptions.
What Makes Properties Different
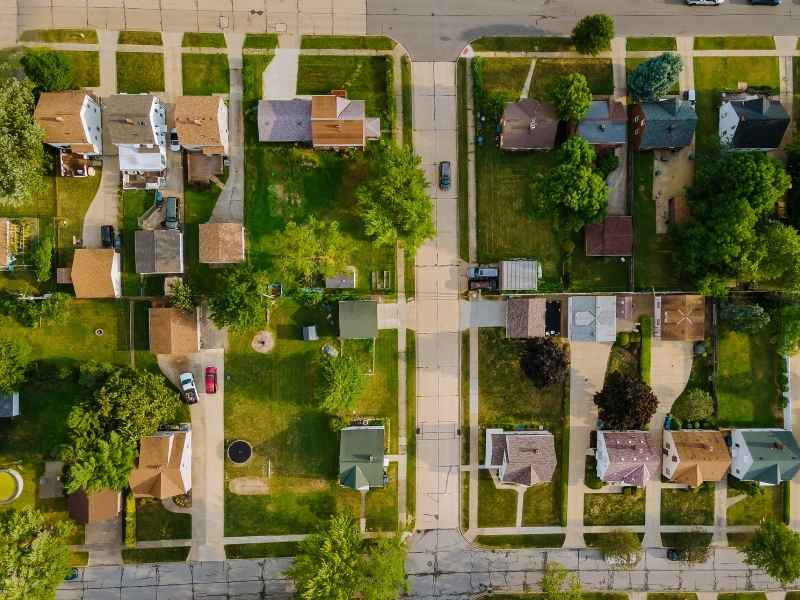
Many neighborhoods have narrow lots and homes built close to the property line. Older housing stock, especially in areas developed before modern zoning rules, can include additions, garages or fences that were never properly recorded. A mortgage survey shows what is really there today, which matters when lot lines are tight and mistakes are easy to make.
Property Features a Mortgage Survey Can Document
A mortgage survey documents the physical features of a property as they exist right now. This includes the building footprint, additions, fences, driveways and other visible structures.
A typical mortgage survey can show:
- Property boundary lines
- The location and size of the main structure
- Garages, sheds or other outbuildings
- Fences, driveways and walkways
- Visible easements or encroachments
This is not the same as a full boundary survey with precise legal measurements. A mortgage survey gives a general but accurate picture of the property, which is usually enough for a lender’s purposes. If a more detailed survey is needed, your lender or title company will typically request one specifically.
Identifying Potential Issues Before Closing
A mortgage survey often catches problems while there is still time to address them. Finding an issue after closing is far more stressful and expensive than catching it beforehand.
Common Issues a Mortgage Survey Can Reveal
Issues a mortgage survey might reveal include:
- A fence or shed that crosses the property line
- A structure built closer to the boundary than local rules allow
- An addition that was never permitted or recorded
- A driveway shared with a neighboring property
Why Tight Lots Raise the Stakes
On a wide suburban lot, a few feet of encroachment might go unnoticed. On a narrow Chicago city lot, the same issue can mean a garage sits partly on someone else’s land. Catching this before closing gives buyers, sellers and their attorneys time to resolve it instead of discovering it after the deal is done.
Supporting Lender and Buyer Due Diligence
A mortgage survey supports due diligence for both the lender and the buyer. The lender uses it to confirm the collateral behind the loan matches expectations. The buyer uses it to confirm they are getting the property they believe they are purchasing.
What Buyers Should Check
Buyers should review the survey alongside the title report and ask questions about anything that looks unclear. This includes checking whether any structures cross the property line, whether easements affect how the land can be used, and whether the survey matches what was described in the listing.
What Lenders Typically Require
Lender requirements for mortgage surveys can vary by loan type, property and lending institution. Some lenders accept an existing survey if it is recent enough. Others require a new one for every transaction. Confirm this requirement early so it does not become a surprise close to closing day.
How Survey Information Helps Reduce Closing Risks
Survey information reduces the risk of a closing being delayed or falling apart over a boundary or structure issue. It gives the title company documentation to support the title insurance policy, and it gives the lender confidence in what they are financing.
Without a current survey, a lender or title company may ask for additional steps before closing, such as extra title endorsements or a follow-up review. These steps take time, and they can push back a closing date buyers and sellers were counting on.
Requirements for mortgage surveys can vary by lender, title company, county and property type. If your closing timeline depends on the survey, confirm what type is needed and when it should be ordered as early as possible in the transaction.
Frequently Asked Questions
Is a mortgage survey the same as a boundary survey?
Not exactly. A mortgage survey gives a general picture of the property’s boundaries and structures for lending purposes. A boundary survey provides precise legal measurements. Some transactions require both, depending on the lender and property.
Who orders the mortgage survey?
This can vary by transaction. Sometimes the buyer orders it, sometimes the lender or title company arranges it. Confirm who is responsible early in the process.
How long does a mortgage survey take?
Timing depends on the property’s size, access and the surveyor’s current workload. A straightforward city lot often moves faster than a larger or more complex property. Ask your surveyor for a timeline once you know a survey is needed.